The midterm elections are fast approaching, and many investors are wondering whether the outcome should change how they are invested. Here, we will examine what history tells us about markets around midterm elections and the policy issues that could shape the investment outlook.
Stocks have historically tended to stay steady regardless of which party wins control of Congress. Our view remains that investors should stay committed to their goals-based investment plans and dispassionately evaluate how policy changes could affect investment objectives rather than react to election headlines and political hype.
1. Three-month returns, post-midterm election
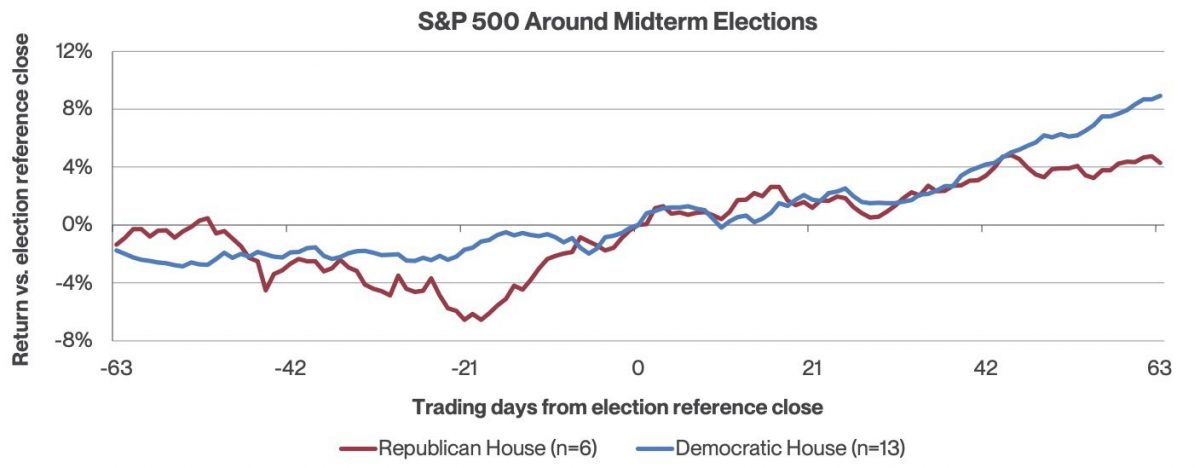
Historically, the S&P 500’s performance has, on average, been positive three months after midterm elections, regardless of the winner of the House of Representatives (Chart 1).
- With Republican House victories, markets have tended to fall in the months leading up to the election, only to begin marching higher in the final weeks leading into the election.
- With Democrat House victories, stocks have climbed steadily into Election Day and rallied further in the following three months.
Examining market performance based on Senate results leads to a similar conclusion: equities have exhibited positive three-month returns after a midterm regardless of which party takes the Senate.
Chart 1: S&P 500 Returns Three Months Before and Three Months After Midterms Since 1950
Bloomberg, calculations by Horizon, data as of 08/30/2026
2. One-year returns after the President’s party loses a House of Congress
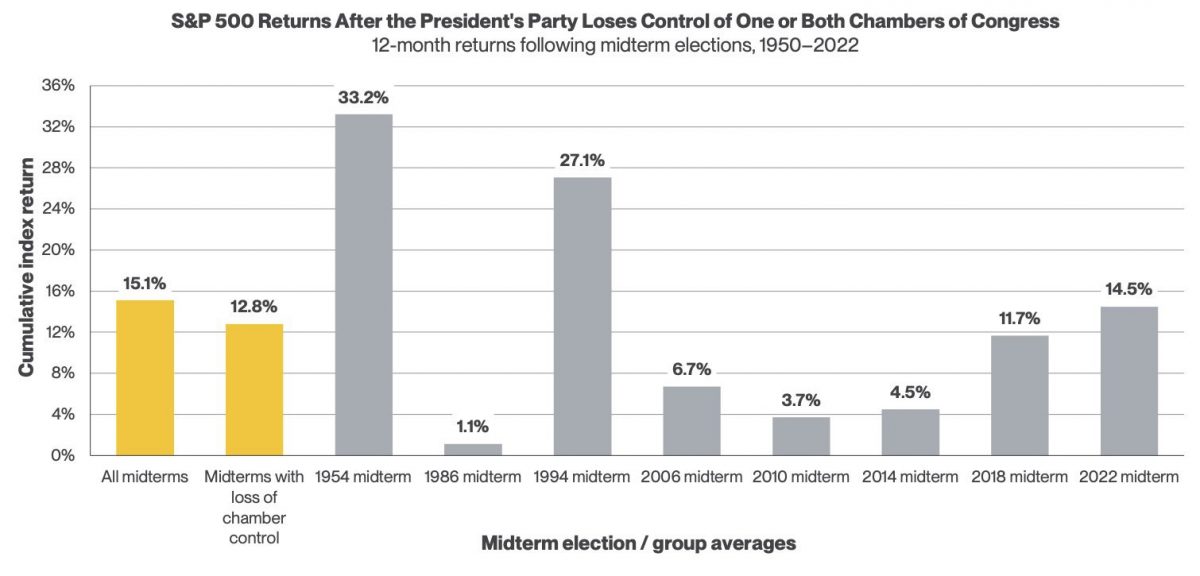
From 1950 through 2022, the President’s party lost control of at least one chamber of Congress in eight of the last nineteen midterm elections. The S&P 500 Index delivered positive returns in the 12 months following each of those elections, averaging 12.8%, compared with 15.1% following midterms overall (Chart 2). Of course, economic conditions and other factors also influence financial markets.
Chart 2: S&P 500 Returns During the First 12 Months After A Midterm Election in Which the President’s Party Loses Control of One or Both Houses of Congress Since 1950
Bloomberg, calculations by Horizon, data as of 08/30/2026
Using history as an indicator, we believe the message is clear. Red or Blue, staying invested is likely to be a solid strategy.
Understanding the Issues: What Could Change After the 2026 Midterms
With the balance of power in Congress and many state governments at stake, this year’s midterms raise an important question for investors: How could the results shape the administration’s agenda and the outlook for taxes, spending, and regulation?
History offers useful perspective, but each election cycle is distinct. We examine the key policy questions and their potential implications for the economy and financial markets, recognizing that campaign promises do not always translate into tangible policy changes or predictable market outcomes.
Policy Outlook
Should this year’s election produce a divided government, the Trump administration would face greater obstacles to advancing its legislative agenda, while the opposition would also face constraints on undoing existing laws or passing new ones. That would likely mean more executive orders and increasing partisan rancor, but few major changes to taxes, spending, and regulation.
For markets, greater policy predictability could reduce uncertainty around corporate earnings and investment decisions. But the potential benefit is a more stable domestic political environment, not necessarily a guarantee of stronger market returns or of a return to the geopolitical status quo.
AI and data centers are a potentially important exception to the broader partisan divide. A July AP-NORC survey found that roughly eight in ten members of both parties supported requiring data-center developers to cover necessary electric-grid upgrades, while majorities in each party also supported limits on new facilities. Bipartisan efforts to protect households from higher electricity costs are already underway. According to GatherGov’s September 10 tally, 270 local jurisdictions had adopted data-center moratoriums this year, with restrictions spanning red and blue states. Shared concerns do not guarantee agreement on solutions, but these actions demonstrate that targeted policy changes, especially at the state and local levels, need not depend on broader agreement in Washington.
AI is, in our view, the single most important theme shaping financial markets and the economy today, driving corporate investment and influencing expectations for earnings and long-term productivity growth. Changes to the policies governing its development could therefore have an outsized impact on the broader investment outlook, with consequences extending well beyond the technology sector. We are closely monitoring the pace of AI investment and the evolving policy landscape, recognizing that even targeted changes could carry market-wide implications.
The upshot: Don’t let candidates’ promises, or how you feel about them, control your investment decisions. Staying committed to your investment plan does not mean ignoring policies that could change the underlying investment case. Vote with your ballot, not your portfolio.